


Nadia's situation
Nadia is 51 and owns a successful medical communications agency. Her company holds £430,000 in cash, and her accountant has identified approximately £180,000 as surplus after considering its working capital requirements, tax liabilities and growth plans.
As most of Nadia’s wealth is tied to the agency, she would like to begin building investments in her own name. She plans to take an additional dividend of £60,000 and make a £60,000 investment, which she intends to hold for at least five years.
Nadia has separate emergency savings and does not expect to need the invested capital during that period. She understands that a VCT would expose her to the higher risks associated with investing in smaller companies.

The adviser's recommendation
Nadia’s accountant first confirms that the proposed dividend is appropriate for the company and calculates the personal tax arising from it. Her financial adviser separately reviews her wider financial position, existing exposure to the agency, investment horizon, need for accessible capital, capacity for loss and attitude to risk.
For the 2026-27 tax year, Nadia’s salary is covered by her personal allowance. Of her existing dividends of £20,500, £500 falls within the dividend allowance and the remaining £20,000 is taxed at 10.75%, producing tax of £2,150. This leaves £17,200 of her basic-rate band available.
Of the additional £60,000 dividend, £17,200 is taxed at 10.75% and £42,800 is taxed at 35.75%. The additional dividend therefore gives rise to income tax of £17,150.
Because Nadia wants to diversify part of her wealth, can invest for at least five years and can accept the higher risks involved, her adviser recommends investing £60,000 in qualifying newly issued VCT shares. Subject to the qualifying conditions and Nadia having sufficient income tax liability, relief at 20% could reduce her overall income tax liability by £12,000.
The dividend remains fully taxable. The VCT relief is claimed separately against Nadia’s overall income tax liability and does not change the tax treatment of the dividend itself.

A note on this scenario
This hypothetical scenario is designed to help advisers think through how this type of planning might apply in practice. Whether it would suit a client will depend on their full financial circumstances, objectives, needs, capacity for loss and attitude to risk, along with the features, risks, charges and tax treatment of any investment being considered. Any recommendation would need to be made by the client’s financial adviser following a full suitability assessment.
This scenario is for illustrative purposes only and does not constitute investment, pension, tax, financial or legal advice. Actual outcomes will depend on investment performance, charges, the client’s circumstances and the tax legislation in force at the relevant time.
What it could mean in numbers
An illustration of Nadia's position after taking the £60,000 dividend, with and without a VCT investment.

Nadia invests the full £60,000 dividend and therefore needs to meet the £17,150 tax liability from other available resources. The potential £12,000 VCT relief reduces her overall income tax liability rather than providing additional cash at the point of investment.
How the £17,150 tax is calculated

Illustrative assumptions
- Nadia is resident in England and subject to the 2026-27 income tax rates and allowances for England, Wales and Northern Ireland.
- Her salary is £12,570 and she receives existing dividends of £20,500 before taking the additional £60,000 dividend.
- She has sufficient income tax liability to claim the potential VCT relief in full.
- She subscribes £60,000 for qualifying newly issued VCT shares and holds them for at least five years.
- Investment performance, fees, charges and any other deductions or reliefs are excluded.
Why the adviser recommends this approach
The recommendation gives Nadia a way to move part of her wealth from the company into an investment held in her own name, reducing her reliance on the future performance of the agency. Her emergency savings and five-year investment horizon reduce her need to access the capital, while her financial position gives her the capacity to accept the higher investment and liquidity risks associated with VCTs.
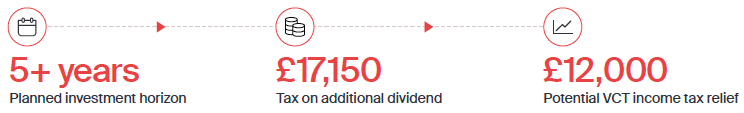
The decision to take the dividend remains separate from the decision to invest in a VCT. On the stated assumptions, the additional dividend gives rise to tax of £17,150, while the VCT investment could provide relief of £12,000 against Nadia’s overall income tax liability.
Key risks and considerations
- Capital is at risk. The value of VCT shares may fall as well as rise, and Nadia may receive back less than the amount invested. VCTs invest in smaller companies, which generally involve greater risk.
- VCTs should be considered as a long-term investment. Disposing of shares within five years of issue will normally result in the initial income tax relief being withdrawn and having to be repaid.
- Income tax relief is not guaranteed. It depends on Nadia’s individual circumstances, including having sufficient income tax liability, the VCT maintaining its qualifying status and the legislation in force, which is subject to change and such changes may be retrospective.
- The dividend and investment are separate decisions. The company must be able to support the dividend, Nadia must fund the resulting tax, and the VCT investment must remain suitable in its own right.
- VCT shares can be difficult to sell. They may trade at a discount to the net asset value, and a sale may take time or realise less than expected. Although many VCTs operate share buyback programmes, these are not guaranteed.
Important Notice
For professional advisers only.
This article is for information purposes only and does not constitute investment, tax, financial or legal advice. It does not constitute an offer to buy or sell an investment or solicit any such invitation.
The information is believed to be accurate at the date of publication, but no representation or warranty, stated or implied, is made or given by any person as to its accuracy or completeness and no responsibility or liability is accepted for any such information or opinion. Tax treatment depends on individual circumstances, and tax rules may change.
Issued by Beringea LLP of Charter House, 55 Drury Lane, London, England WC2B 5SQ. Registered in England and Wales under number OC342919. Authorised and regulated by the Financial Conduct Authority under number 496358.


